1031 Exchange Oregon
Selling Oregon business or investment real estate and reinvesting in another lets an owner push the capital gains bill into the future. As simple as this may sound, it often involves very complex rules and strict timelines, which can complicate the entire process.
Last updated 12 November 2026 · Sources for this page
An Oregon exchange has to satisfy the IRS and the Oregon Department of Revenue at the same time, and the state adds a reporting duty of its own once your replacement property sits outside Oregon. Oregon's clawback provision and its reporting requirements add steps that a federal-only checklist misses. Working with the right Qualified Intermediary can simplify the process and help you keep track of each rule.
We follow how Oregon law layers onto the federal code. Our job is to keep your money safe while it is held and to prepare paperwork that matches both sets of rules. To plan your exchange, book a call with us today. Our office is in Los Angeles (1180 S. Beverly Drive, Suite 500); we have no Oregon office and work with your Oregon title or escrow company remotely. Buying out of state? Read keeping an Oregon exchange history first. For city-level closing detail, see our Portland 1031 exchange guide or the full list of locations we cover.
With a professional history managing transactions ranging in price from $100,000 to over $100M, our company combines genuine business acumen, real estate insight, and financial literacy.
Michael Bergman, CPA, President & CEO
Oregon exchange facts at a glance
| Item | Figure | Source |
|---|---|---|
| Withholding when a nonresident sells | Smallest of 4% of the price, 8% of the Oregon-taxable gain, or the net proceeds; sales of $100,000 or less are exempt | ORS 314.258; Form OR-18-WC instructions (2025) |
| Form OR-24 | Filed for the exchange year and every year until the out-of-state replacement is disposed of | Form OR-24 instructions (rev. 08-18-23) |
| Later taxable sale of the out-of-state replacement | Oregon adds back the deferred gain, measured at the lesser of two values | ORS 316.738 |
| Exchange facilitator fund protection | $1 million fidelity bond or deposit, or a qualified escrow or trust needing two signatures | ORS 673.810(1) |
| Exchange facilitator E&O | At least $250,000 of E&O insurance, or an equal deposit | ORS 673.810(2) |
| Median owner-occupied home value | $477,600 in Oregon; $332,700 in the U.S. | Census ACS 2020-2024, B25077 |
| Median gross rent | $1,525 in Oregon; $1,413 in the U.S. | Census ACS 2020-2024, B25064 |
| Renter-occupied homes | 36.7% of occupied homes in Oregon; 34.8% in the U.S. | Census ACS 2020-2024, B25003 |
| People who moved from Oregon to another state in a year | 125,031, or 2.98% of residents one year earlier | Census ACS 2020-2024, B07403 |
In this guide
- How Section 1031 applies to Oregon real estate
- How an Oregon exchange works, step by step
- The delayed exchange and nonresident withholding
- Commercial real estate in an Oregon exchange
- Oregon housing markets by county
- What Universal Pacific does on an Oregon exchange
- Costs, timelines and coverage
- Oregon and federal requirements
- Keeping an Oregon exchange history
- Finding a qualified intermediary
- Oregon 1031 exchange questions
- Sources for this page
How Section 1031 Applies to Oregon Real Estate
Oregon owners use Section 1031 of the Internal Revenue Code, a federal provision that postpones tax on the gain when investment real estate is traded. Instead of paying taxes immediately, investors can reinvest the sale proceeds from the relinquished property into another qualifying like-kind property.
Deferral starts with use: the property you sell and the one you buy both have to be kept for a business or as an investment. This means that personal properties such as primary residences and vacation homes generally do not qualify (see the IRS summary, Like-Kind Exchanges: Real Estate Tax Tips). Most delayed exchanges also use a Qualified Intermediary; Treas. Reg. §1.1031(k)-1(g)(4) treats one as a safe harbor, and it stands between you and the money.
Taking possession of sale proceeds can trigger constructive receipt, which the Internal Revenue Service (IRS) considers taxable. Debt matters too: if the loan paid off at the sale is larger than the loan on the replacement, the difference counts like cash received unless you put in cash of your own at the purchase (Treas. Reg. §1.1031(d)-2). Additionally, the IRS sets strict timelines for identifying replacement properties and completing the exchange.
The rules are federal, and Oregon owners rely on them for the same reasons owners elsewhere do: to preserve wealth, grow their portfolios, diversify across property types, and support their long-term real estate investment goals without immediate tax consequences.
How an Oregon 1031 Exchange Works, Step by Step
A 1031 exchange follows a series of intricate steps that Oregon real estate investors must follow to stay compliant with the 1031 rules and avoid creating taxable liability. They are as follows:
Engage a Qualified Intermediary
Begin by talking to a Qualified Intermediary before the sale closes. As previously mentioned, a QI is a neutral third party responsible for holding the sale proceeds, preparing the necessary documentation, and running the exchange side of the transaction, while your title or escrow company handles the closings and your CPA handles the tax returns.
Sell the Relinquished Property
A 1031 exchange starts when an investor decides to sell an existing investment or business property in exchange for another like-kind real property. To do this, the investor lists the business property and waits for a buyer to come along. This property could be a rental, multifamily building, or other income-producing real estate in Oregon.
At closing, the buyer pays the Qualified Intermediary rather than you, and the cash waits in an exchange account until the purchase. And as previously stated, this is critical for deferring tax liability.
Identify a Replacement property
The investor then has a 45-day window, counted from the sale, to name what will be bought. To defer all of the gain, the replacement should cost at least as much as the net sale price and absorb all of the exchange cash; buying for less is allowed, but the difference is taxable boot (26 U.S.C. §1031(b)). The identification must be signed, put in writing and delivered to the QI no later than the 45th day.
Complete the Exchange
The purchase deadline is 180 days. That window overlaps the 45 days rather than following them, so the total is not 225 days but 180 days after the sale. An earlier extended due date for that year's return takes its place (Treas. Reg. §1.1031(k)-1(b)(2)). The QI releases the held money at the purchase, and the seller conveys title straight to the investor.
However, it is important to note that this step-by-step process is typically for the standard/delayed exchange. Other exchanges, such as the reverse exchange, improvement exchange, and simultaneous exchange, follow different orders. A reverse exchange flips that order, usually under the parking arrangement in Rev. Proc. 2000-37.
The Oregon Delayed Exchange and Nonresident Withholding
In Oregon, the usual pattern is a delayed exchange: list and close the relinquished property, leave the money with the qualified intermediary, and only then contract for the next asset. The walk-through in How an Oregon 1031 Exchange Works, Step by Step is that delayed sequence. The 45-day and 180-day limits begin together at the Oregon closing and overlap; they are not added end to end. Treas. Reg. §1.1031(k)-1(b)(2) shortens that second window when the tax return for the year of the sale, with extensions, is due first. Property that is named late, or acquired after the exchange period expires, typically loses deferral.
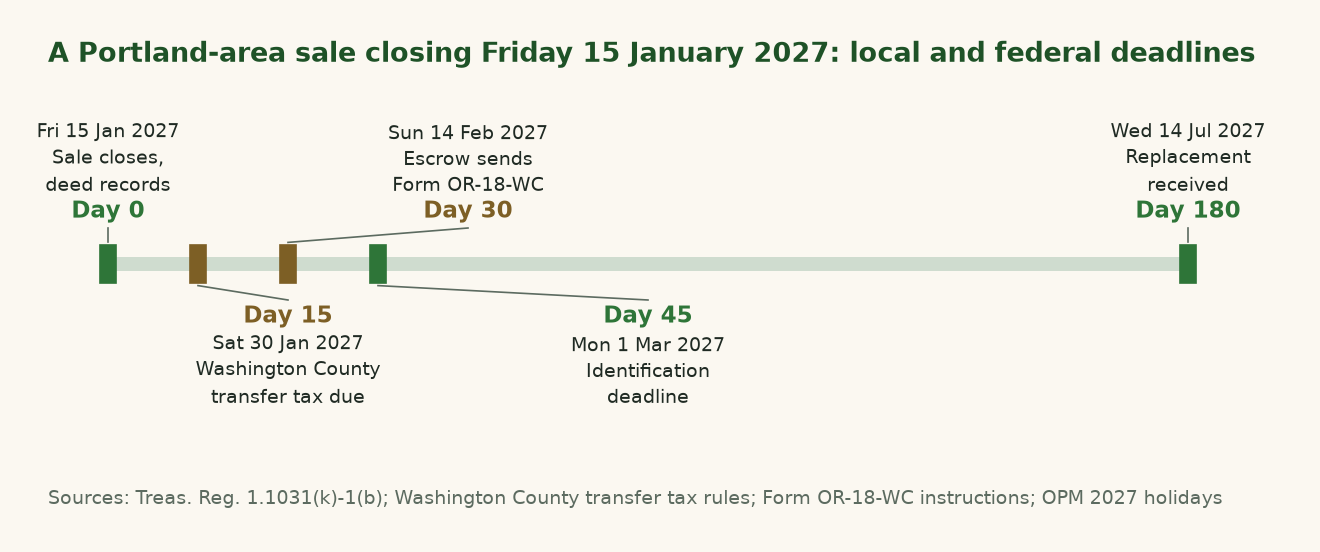
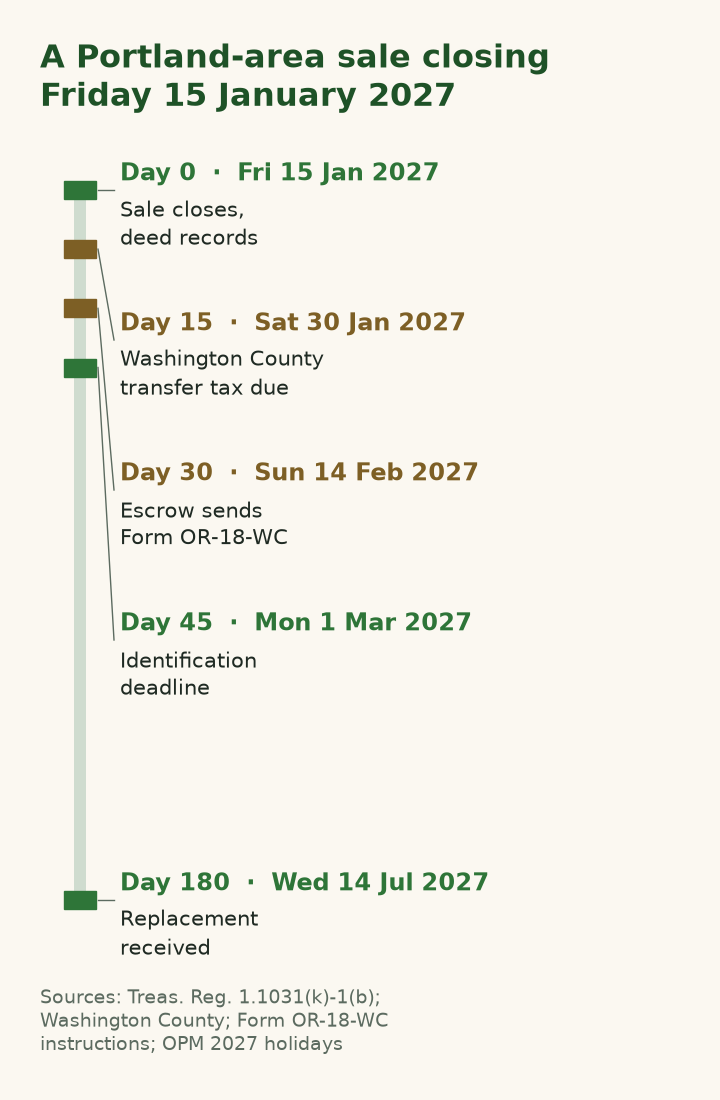
The delayed form is also the one that most often meets Oregon's nonresident conveyance reporting. When a nonresident sells Oregon real property, the closer reports the transfer on Form OR-18-WC; an exchange is disclosed on that form rather than ignored. The rule is set out below, and our Portland 1031 exchange page places the dates on a sample closing calendar. If the replacement you buy is outside Oregon, Form OR-24 and the later add-back under ORS 316.738, covered later on this page, are the follow-on Oregon pieces.
Withholding When a Nonresident Sells Oregon Property
Under ORS 314.258, the escrow agent on a sale by a nonresident (or an attorney who closes the sale through a client trust account) must collect a completed Form OR-18-WC and, unless an exemption applies, hold back the smallest of three amounts: 4% of the sales price, 8% of the gain that is includable in Oregon taxable income, or the net proceeds paid out to the seller (Form OR-18-WC instructions, 2025). A sale of $100,000 or less is exempt, and so is a sale where the entire gain is excluded under IRC Section 121 as a principal residence.
An exchange changes two of those numbers. Part D of the 2025 Form OR-18-WC has a line for gain excluded under a federal nonrecognition section, with the IRC section written in, so deferred exchange gain can come out of the 8% figure. Money sent to the qualified intermediary is not net proceeds either: in the instructions' example of a $500,000 commercial building, $200,000 of the cash due to the seller goes to a qualified intermediary, so only the $75,000 escrow will pay out is entered as net proceeds. If the seller leaves Part D blank, the agent withholds 4% of the price or, if less, all of the net proceeds.
The amount withheld is not a final tax. It is credited to the seller's Oregon account for the year of the sale and claimed on Form OR-40-N or OR-40-P (Form OR-20 for a C corporation). The agent sends the form and payment within 20 days of paying out the proceeds, or within 30 days of closing if nothing is paid out, so the paperwork usually lands before the day-45 identification deadline.
Commercial Real Estate in an Oregon 1031 Exchange
Yes. Commercial inventory in Oregon (a warehouse in the Willamette Valley, a retail box, an office, a plant, a mixed-use project, or acreage held as an investment) can be swapped for a different qualifying type, including a rental house, provided both interests are real property and the use test is met (Treas. Reg. §1.1031(a)-1(b)). Those same day-45 and day-180 limits apply whether the building is commercial or residential.
What does change is the local closing work: different leases, environmental reviews, and county recording, and, if you plan to build or renovate with exchange funds, an improvement exchange rather than a plain delayed purchase (Treas. Reg. §1.1031(k)-1(e)). Your broker and counsel lead that due diligence. We do not find or list Oregon commercial properties; we hold the funds, track the 45- and 180-day dates, and close the intermediary side of whichever identified property you and your advisors choose.
Oregon Housing Markets by County
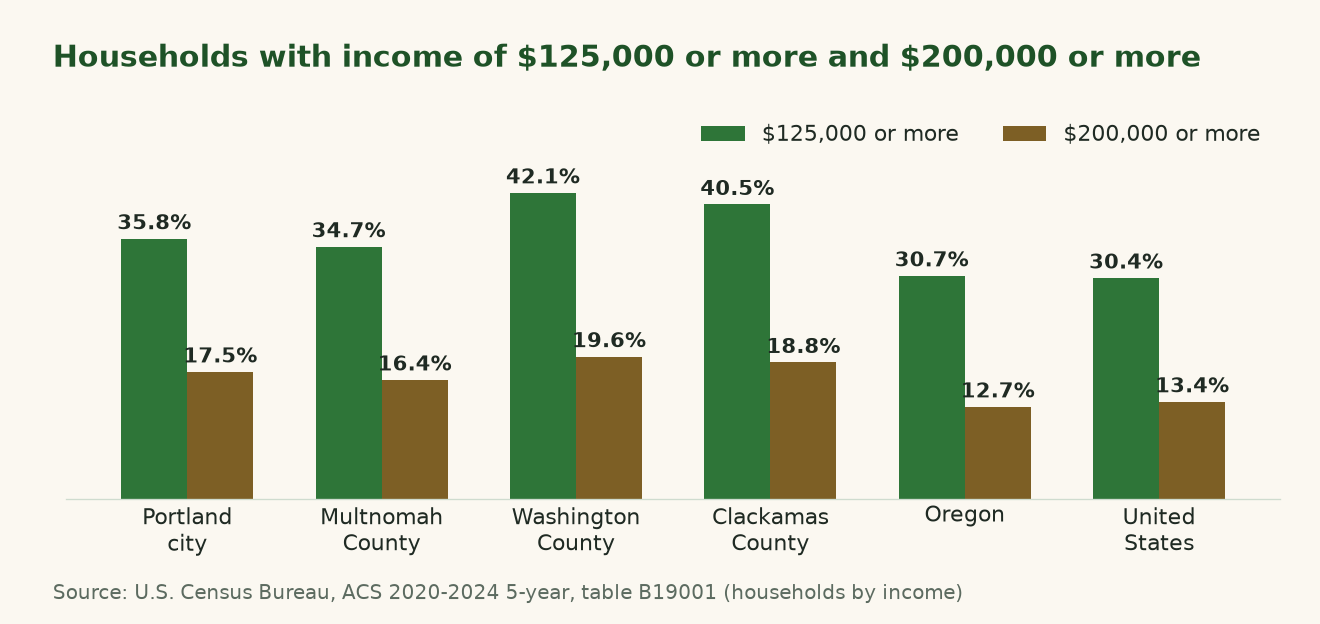
Oregon exchanges are not all Portland exchanges. The Census Bureau's 2020-2024 American Community Survey puts the median owner-occupied home value at $477,600 statewide, against $332,700 for the U.S., and the spread between counties is wide. The table compares the three Portland-area counties, the city of Portland, the Eugene and Salem counties, and Deschutes County, which includes Bend.
| Area | Median home value | Median gross rent | Renter-occupied homes | Median household income |
|---|---|---|---|---|
| Portland city | $581,500 | $1,655 | 48.0% | $90,919 |
| Multnomah County | $552,700 | $1,646 | 46.6% | $88,766 |
| Washington County | $588,000 | $1,849 | 39.2% | $107,772 |
| Clackamas County | $611,000 | $1,758 | 29.3% | $103,517 |
| Lane County (Eugene) | $430,600 | $1,355 | 40.3% | $71,544 |
| Marion County (Salem) | $416,400 | $1,414 | 37.7% | $77,351 |
| Deschutes County (Bend) | $650,900 | $1,787 | 30.0% | $92,758 |
| Oregon | $477,600 | $1,525 | 36.7% | $83,011 |
| United States | $332,700 | $1,413 | 34.8% | $80,734 |
Source: U.S. Census Bureau, ACS 2020-2024 5-year estimates, tables B25077, B25064, B25003 and B19013.
Deschutes, Clackamas and Washington counties have the highest median values in the table, while Lane and Marion counties sit below the state median, so an owner who sells in the first group and buys in the second is moving into a market where the typical home is valued lower. Multnomah County has the largest share of renter households among the counties shown, at 46.6%. These are medians across all homes in each area, not prices for investment property, so use them as context, not to value a particular building.
Most Oregon housing is single-family: 62.7% of homes are detached houses, 7.0% are in buildings of two to four units and 7.1% are mobile homes (table B25024). An exchange can move between those types, since real property held for investment or business is generally like-kind to other U.S. real property. If the replacement is across the Columbia River, our Seattle 1031 exchange page explains Washington's real estate excise tax, which an exchange does not defer. For Portland's city and Metro taxes see the Portland guide, and the locations page lists every city we cover.
What Universal Pacific Does on an Oregon Exchange
Proven track record: We've helped real estate investors in Oregon continually defer capital gains taxes when selling investment properties, whether within the state or out-of-state. We also keep the process tied to the IRS's strict rules and timelines, so that you can have more capital working for you.
Expertise in handling complex exchanges: Our team specializes in handling complex exchanges, be it reverse exchanges, simultaneous exchange, or improvement exchange. We guide you through each step of the process with clarity, ensuring that complex terms are broken down into understandable words.
Strong regulatory compliance: Universal Pacific maintains strict compliance with the IRS regulations and established revenue procedures. This approach helps investors mitigate the risks associated with a tax-deferred exchange and avoid costly mistakes that could jeopardize their tax-deferral benefits.
Vast experience across property types: We have also facilitated different like-kind exchanges across a wide range of real estate assets, including commercial buildings, retail centers, multifamily properties, vacant land, industrial facilities, and mixed-use investments.
Safe management of client funds: Proceeds are segregated by client in a dedicated exchange account. That separation keeps your exchange money apart from other funds and supports the rule that you never receive the proceeds yourself.
A consultation costs nothing and commits you to nothing. Bring your sale timeline and a rough idea of where you might buy, especially if it is outside Oregon, and we will map the federal deadlines and the Oregon filings that apply before you sign a listing or sale agreement.
Oregon 1031 Exchange Costs, Timelines and Coverage
A 1031 exchange cost in Oregon is made up of several separate charges, and the total depends on the property value, the structure and the number of closings. A major aspect of this cost comes from the QI fees, which depend mainly on the exchange structure; reverse and improvement exchanges cost more than a standard delayed exchange because they need a titleholder entity and more documents.
Other fees include title and escrow fees, legal fees, and appraisals and inspections, each quoted by the provider for your property and county.
Recording fees are charged per deed by the county where the property sits. It is also important to consider loan and financing costs if a mortgage is involved, as well as holding costs for taxes, insurance, and maintenance on the replacement property.
Nonresident sellers are often surprised by Oregon's closing withholding, reported on Form OR-18-WC. The amount is an estimated payment credited on your Oregon return, not a final tax, and an exchange is reported on the form rather than ignored. The rule and the exchange lines on the form are set out in the withholding section above.
The identification and purchase windows described above apply to every exchange. Missing these timelines could result in the disqualification of the transaction. In view of this, working with an experienced QI is essential to ensure compliance.
Oregon Service Coverage
Our intermediary work reaches across Oregon's real estate market, including Portland, Eugene, Bend and Salem. Each county records its own deeds, and we coordinate with the escrow firm you choose. Portland has its own Portland 1031 exchange page covering its city and Metro taxes.
Finding the replacement property is your decision, usually with your broker; our part is making sure the IRS 45 and 180-day timelines are tracked so the identification and the purchase can still qualify.
Common 1031 Exchange Issues in Oregon
One of the biggest challenges many investors in Oregon encounter when performing a 1031 exchange is finding the right replacement property, especially in cities like Portland. This is because the IRS places strict rules on the new investment property to invest the sale proceeds into.
Most times, it can be difficult to find a new property that costs as much as the old one, especially for investors who do not have enough cash to add to the purchase, or those who cannot obtain a loan. This sometimes leads to missed deadlines, or to a purchase below the sale price that leaves some gain taxable. Buying for less does not cancel the exchange; it means part of the gain is recognized now.
Complex ownership structures such as LLCs, partnerships, or trusts can also add more complexity to the entire process, making it difficult to maintain compliance. Title and lien issues can also arise, especially with older or multi-owner properties, which can delay closing.
A further problem shows up years later: missing records. When an out-of-state replacement is eventually sold, someone has to know the adjusted basis and value at the time of the exchange. If those numbers were never written down, rebuilding them is slow and costly, which is why the ledger below matters.
Oregon and Federal Requirements
Oregon's personal income tax starts from federal taxable income (ORS 316.048), so Oregon follows the federal 1031 result: if the transaction qualifies federally for a tax deferral, Oregon tax is deferred as well. Where the two part company is reporting. The Oregon Department of Revenue requires Form OR-24 only when Oregon property is exchanged for property outside Oregon. The form's instructions are explicit: "Don't use this form when exchanging property in Oregon for other property in Oregon" (Form OR-24 instructions). The Department's 2025 Publication OR-17 says the same in its like-kind exchange section, which cites ORS 316.738 for individuals and ORS 317.327 for corporations.
Where the form applies, it is due for the exchange year and annually afterward until the out-of-state property is gone, even when nothing else is filed with Oregon. Oregon also has a clawback provision (ORS 316.738), which lets the state tax the postponed gain at a later taxable sale.
In Oregon, Qualified Intermediaries are referred to as exchange facilitators and are subject to specific statutory regulations that do not apply on the federal level. These laws are set in place to protect investors' exchange funds and reduce the risk of fraud and mismanagement during the exchange process. Under ORS 673.810, a facilitator must at all times use one of these fund protections:
- a fidelity bond or bonds totaling at least $1 million;
- $1 million or more placed with a financial institution as cash, securities or irrevocable letters of credit;
- holding the money in a qualified escrow or qualified trust from which nothing is withdrawn unless both you and the facilitator sign; or
- named-insured status on fidelity bonds totaling at least $1 million.
Separately, the statute requires E&O coverage of $250,000 or more, an equal deposit in its place, or named-insured status under such a policy. ORS 673.815 adds a prudent investor standard for exchange funds, aimed at liquidity and preservation of principal.
Keep an Oregon Exchange History Through the Next Replacement
Oregon's interest in your deferred gain does not end when the replacement closes in another state. The Census Bureau estimates that 125,031 people who lived in Oregon one year earlier had moved to another state, about 2.98% of that population, so a seller who later moves away is not unusual. Whether you stay or leave, the add-back in ORS 316.738 needs numbers from the day the exchange was completed, and those numbers are easiest to capture at that closing.
Record the Original Oregon Gain
When the exchange closes, note four things for each out-of-state replacement: the completion date, the adjusted basis and market value on that day, and which Oregon property it replaced. Fair market value usually comes from the purchase price, but an appraisal is better evidence if the price included anything unusual. Keep the settlement statements from both closings and the Form 8824 with these figures.
Decide Who Files Form OR-24 Each Year
The annual OR-24 is a tax filing, so it belongs with whoever prepares your Oregon return, usually your CPA. We are the intermediary: we can provide the exchange documents and dates, but we do not prepare returns. Put the filing on your preparer's list every year, including years when you would not otherwise file in Oregon.
Keep the Chain When You Exchange Again
If you later exchange the out-of-state replacement for another property, the deferral continues, and so does the record. Keep each exchange's figures separately, since a new OR-24 is needed for each exchange, and link every replacement back to the Oregon property where the chain started.
How the Oregon Portion Is Measured at a Taxable Sale
When the replacement is finally sold in a taxable sale, ORS 316.738 adds to income the difference between its adjusted basis on the exchange completion date and the lower of two values: its fair market value on that date, or its value when the gain is recognized. If the basis is higher than that lower value, the difference is subtracted instead. The table shows the arithmetic for a hypothetical replacement with a $300,000 adjusted basis and an $800,000 value when the exchange was completed.
| Later sale value | Lower of $800,000 and sale value | Oregon addition (or subtraction) |
|---|---|---|
| $1,000,000 | $800,000 | $500,000 added |
| $700,000 | $700,000 | $400,000 added |
| $250,000 | $250,000 | $50,000 subtracted |
In plain terms, appreciation after the exchange is not pulled into the Oregon figure by this formula, while a fall in value reduces it. The add-back is part of Oregon's income tax at its normal rates, so the deferred Oregon tax is postponed, not forgiven.
Exchange history ledger
| Record | Why it matters | Keep until |
|---|---|---|
| Oregon sale settlement statement | Shows the price and date of the original exchange | The last replacement in the chain is sold |
| Replacement settlement statement | Supports the value on the completion date | Same |
| Form 8824 for each exchange | Shows deferred gain and basis carried over | Same |
| Adjusted basis schedule | Needed for the ORS 316.738 calculation | Same |
| Each year's Form OR-24 | Shows the annual report was made | Same |
| Residency history | Decides which Oregon return reports the gain | Same |
Finding a Qualified Intermediary in Oregon
When searching for a QI, it is important to choose a firm with a strong track record of successful exchanges and deep knowledge of both federal rules and Oregon-specific requirements. Also, look out for how they handle clients' funds, check to see if they mingle them together or place them in secure segregated accounts.
A good QI should be able to guide you through the exchange process with integrity and be honest about their fees. Ask which of Oregon's facilitator protections described above the firm uses and request proof, such as the bond or the E&O policy declaration. It also helps to get reviews from past clients they've worked for to see if they are experienced, transparent, and professional in their duties.
Planning Your Oregon Exchange Before You List
Doing an exchange alone is hard: the steps are many and the deadlines do not bend. In Oregon, claw-back provisions, strict reporting requirements, and a competitive real estate market can add more layers of complexity.
Even seasoned investors find the exchange demanding, and first-timers more so. It is important to work with a Qualified Intermediary well-versed in both federal-level requirements and Oregon-specific income taxes.
We guide you through every step of the process, breaking complex terms down into very easy-to-understand words and keeping your transaction aligned with applicable IRS's rules and regulations. Contact us today to start your exchange.
Oregon 1031 Exchange Questions
Here are some common questions about a 1031 exchange in Oregon, along with their respective answers.
What Are the Time Limits for a 1031 Exchange in Oregon?
Candidates must be listed within 45 days, under one of the three identification rules. Closing must follow within 180 days of the sale, or sooner in the case explained in the steps above. Weekends and holidays do not stretch either deadline. Only an IRS postponement notice issued under 26 U.S.C. §7508A can move them.
Can I Do a 1031 Exchange on a Vacation Property in Oregon?
Yes, a vacation property in Oregon can qualify, but only if it meets the IRS like-kind requirements. Occasional family use is allowed, but the house has to function as a rental. The IRS safe harbor (Rev. Proc. 2008-16) asks for two years of ownership immediately before the swap and at least 14 days of rental at market rates in each of those two years.
Your own days at the house in each year are capped at 14 or, if higher, one-tenth of the days rented at market rates. If these conditions are met, the IRS will not challenge the property as being held for business or investment purposes rather than personal use. A vacation home you buy as the replacement faces the mirror-image test for two years following the swap.
Are There Any 1031 Exchange Companies in Oregon?
Yes, 1031 exchange companies serve in Oregon. Universal Pacific offers extensive 1031 exchange services in Oregon and beyond, with in-depth knowledge on how to navigate Oregon-specific nuances while still maintaining compliance with the IRS rules and regulations.
What Are the Tax Implications of a 1031 Exchange in Oregon?
When the exchange is done correctly, Oregon income tax waits along with the federal tax. However, those taxes are deferred and not eliminated, and will be triggered once the replacement property is sold without another exchange.
How Do I Find a Qualified Intermediary for a 1031 Exchange in Oregon?
Start by identifying firms that specialize in 1031 exchanges and have a strong record of compliance and fund security. It is also important to confirm that the QI uses secure, segregated accounts to hold funds and maintains appropriate bonding and insurance. Universal Pacific works with Oregon real estate investors on that basis, with CPA supervision and hands-on support throughout the exchange.
Who Can Use a 1031 Exchange, and What Are the Tax Advantages?
A 1031 exchange can be used by individuals, corporations, and limited liability entities that own qualifying investment or business property. The main advantage is the ability to defer capital gains taxation while reinvesting into new property, allowing investors to preserve equity and continue growing their portfolios. It is advisable to consult experienced exchange professionals or financial advisors before initiating an exchange.
How many Form OR-24s do I file if I made two exchanges?
One per exchange. The instructions say that if you made more than one like-kind exchange, each is reported on a separate form, and each form continues every year until that exchange's replacement property is disposed of.
Which Oregon return carries Form OR-24 for an individual?
Attach it to the return you file: Form OR-40 for full-year residents, OR-40-N for nonresidents or OR-40-P for part-year residents, and check the "Form OR-24" box on that return.
Where do partnerships, corporations, trusts and estates file Form OR-24?
Partnerships include it with Form OR-65. Corporations include it with Form OR-20, OR-20-INC or OR-20-S. Trusts and estates include it with Form OR-41, the Oregon fiduciary return. Each checks the "Form OR-24" box.
Can Form OR-24 be filed when I have no Oregon return to file?
Yes, through Revenue Online by logging in to your account. If you do not have an account you may be able to create one, but the instructions say you must have filed an Oregon return before to do so. Set this up while you still have your earlier filings at hand.
If I move out of Oregon, is the deferred Oregon gain forgiven?
No. Publication OR-17 says that if you were an Oregon resident when the exchange took place, you report the Oregon portion of the gain when the gain is reported on your federal return. If you were a nonresident at the exchange or when the gain is reported, you file Form OR-40-N to report it.
How is a single-member LLC seller treated for Oregon withholding?
The Form OR-18-WC instructions tell escrow to disregard an LLC owned entirely by an individual, by spouses filing a joint return, or by a C corporation, and to base the requirement on the owner. So a nonresident individual's single-member LLC is treated as that nonresident.
How long is the Form OR-18-WC kept, and how is the payment credited?
The escrow or other authorized agent keeps it for six years from the closing date, and you should keep your own copy. Any payment is credited as an estimated tax payment for the year of the sale; individuals claim it on Form OR-40-N or OR-40-P.
Does Oregon's facilitator law cover an intermediary based in another state?
It depends on what the intermediary does in Oregon. ORS 673.800 covers firms that act for a fee as qualified intermediaries, accommodation titleholders, or qualified trust or escrow holders, and firms with an Oregon office for that business. Among its exclusions: an intermediary whose funds came from selling non-Oregon property, and a titleholder with no Oregon title. Selling Oregon property is the situation the law is aimed at.
Can an exchange facilitator mix my exchange funds with its own money?
No. Under ORS 673.815, a facilitator that knowingly commingles exchange funds with its operating accounts fails the prudent investor standard, and so does one that lends or transfers them to an affiliate, except to an accommodation titleholder under a qualified exchange accommodation agreement. The statute also says exchange funds are not subject to execution or attachment on a claim against the facilitator.
What is a delayed 1031 exchange in Oregon?
It is a sell-first exchange. Once the sale has funded, you have a 45-day window to designate the next property and a 180-day window to receive it. An earlier due date on the sale-year return can shrink the second window. The delayed-exchange section above walks through those clocks and points to the Oregon reporting that often travels with this structure.
Can I do a 1031 exchange with commercial real estate in Oregon?
Yes. A warehouse in Eugene or a retail pad in Salem can go into an exchange if you are holding it as an investment or for your business, and the property you acquire is held the same way. Day 45 and day 180 still govern. The commercial section above has the regulatory citations.
Choosing an Oregon Qualified Intermediary for 1031 Exchange Transactions
Every Oregon file is supervised by a CPA. Each client gets individual attention and careful handling of the details across Oregon and out-of-state replacements alike.
Sources
Federal law and regulations
- 26 U.S.C. §1031Exchange rules, 45/180-day deadlines, boot and U.S.-property limit (Cornell LII)
- Treas. Reg. §1.1031(k)-1Deferred exchanges: exchange period, identification, qualified intermediary safe harbor (eCFR)
- Treas. Reg. §1.1031(a)-1Like-kind standard and business or investment use (eCFR)
- Treas. Reg. §1.1031(d)-2Liabilities assumed or paid off treated as cash received (eCFR)
- 26 U.S.C. §7508ADisaster postponement of tax deadlines (Cornell LII)
IRS guidance
- Fact Sheet FS-2008-18IRS overview of like-kind exchanges of real estate
- Like-Kind Exchanges: Real Estate Tax TipsIRS summary of the rules and Form 8824 reporting
- Instructions for Form 8824IRS; reporting an exchange and the basis carried over
- Rev. Proc. 2000-37Reverse exchange safe harbor; Internal Revenue Bulletin 2000-40
- Rev. Proc. 2008-16Safe harbor for dwelling units, including vacation homes; Internal Revenue Bulletin 2008-10
State law and tax
- ORS chapter 316Personal income tax: federal starting point (316.048), out-of-state add-back (316.738); 2025 edition
- ORS 314.258Withholding when a nonresident conveys Oregon real estate; 2025 edition
- ORS 673.800 to 673.815Exchange facilitator coverage, bond or deposit, E&O and prudent investor rules; 2025 edition
- Form OR-24 instructionsOregon Department of Revenue; Oregon property exchanged for out-of-state property (rev. 08-18-23)
- Form OR-24Oregon Department of Revenue; the annual like-kind exchange report
- Publication OR-17 (2025)Oregon Department of Revenue individual income tax guide; like-kind exchange section
- Form OR-18-WC instructions (2025)Oregon Department of Revenue; exemptions, the 4%/8%/net proceeds rule, deadlines and examples
- Form OR-18-WC (2025)Oregon Department of Revenue; withholding report for nonresident sellers
- Personal income taxOregon Department of Revenue; 2025 tax year rate charts and filing information
Data
- American Community Survey 2020-2024, 5-year estimatesU.S. Census Bureau summary file; tables B25077, B25064, B25003, B25024, B19013, B19001 and B07403; Oregon, counties, Portland city and U.S.
Disclaimer: This page is for general informational purposes only and is not tax or legal advice. Oregon 1031 exchange rules are complex, and their application depends on your specific facts. Tax laws change, and each situation is different. Consult a qualified intermediary and a licensed tax advisor before acting.
Ready to defer your capital gains?
Speak with a CPA-led qualified intermediary. We line up your exchange before you sell — not after.