01 Step 01 of 08
Sign the sale contract
The exchanger signs a contract to sell a relinquished property to the buyer.
Universal Pacific is a national 1031 exchange company that acts as your Qualified Intermediary, with the exchange handled by licensed CPAs and your funds held in a bank custody account. A 1031 exchange lets you defer capital gains tax when you sell investment real estate and reinvest in a like-kind replacement property. We handle delayed, simultaneous, reverse, and improvement exchanges nationwide.
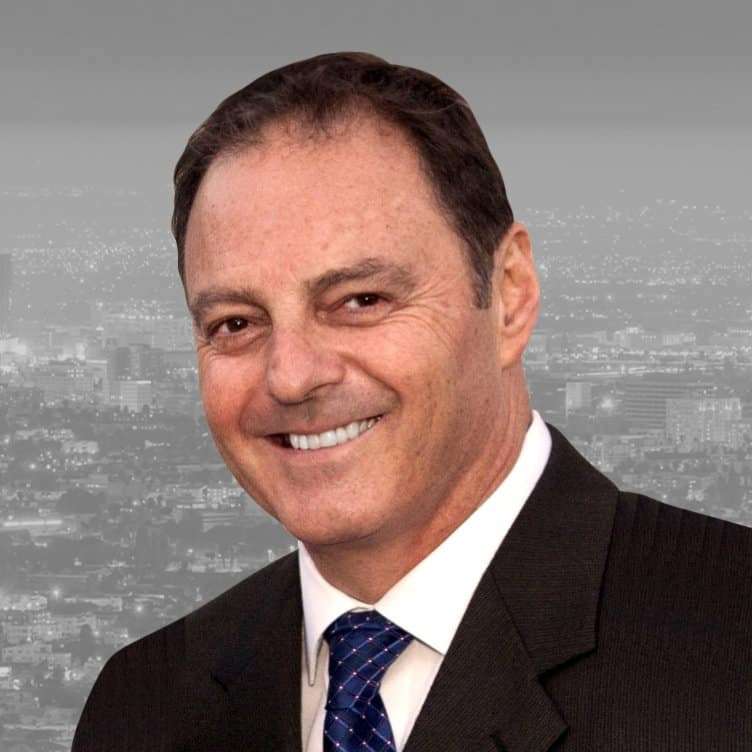
Michael Bergman, CPA
President & CEO · California CPA
Hundreds of Millions
in transactions completed
$2 Million
Errors & Omissions insurance
Since 1990
CPA licensed
All 50 States
nationwide service
Universal Pacific is a national 1031 exchange company known for white-glove service, secure fund handling, and IRS-compliant exchange handling.
Start an ExchangeUnder Section 1031 of the United States Internal Revenue Code (26 U.S.C. § 1031), the exchange of certain types of property may defer the recognition of capital gains or losses due upon sale, and hence defer any capital gains taxes otherwise due.
Existing property is sold, and a replacement property is purchased within 180 days.
Learn more →Simultaneously transfer ownership of both the relinquished property and the replacement property.
Learn more →The replacement property is identified and purchased before the relinquished property is sold.
Learn more →This type of exchange occurs when an existing owner elects to either make improvements to an identified replacement property or construct a new replacement property.
Learn more →Not all 1031 exchange companies are built the same. At Universal Pacific, we've built more than a process—we've built a reputation. Our clients include real estate attorneys, brokers, CPAs, and high-volume investors who depend on airtight execution for six- and seven-figure transactions. They choose us not for convenience, but for confidence. Here’s what sets us apart:
We've supported 1031 exchanges across every asset class—from multifamily portfolios and land development to industrial and retail swaps.
Our internal team doesn't outsource compliance. Every exchange is reviewed and documented by licensed tax professionals. Qualified intermediary services are reviewed and overseen by Michael Bergman, CPA (California CPA, licensed since 1990).
With $2 million in E&O insurance, segregated accounts, and multi-layered authorization, we treat every exchange like it's our own capital at stake.
From complex reverse exchanges to multi-asset rollovers, we specialize in solving high-dollar, deadline-driven transactions with precision.
If you’re moving more than just real estate, you need more than just a facilitator.
Eight coordinated steps, tracked end to end against the 45- and 180-day IRS deadlines. Scroll to follow the sequence.
Straight from our clients — 5.0 out of 5 stars across 16 Google reviews.
We follow a simple yet very stringent process of keeping exchange funds secure. Upon the sale of the relinquished property, all exchange funds are wired from the sale escrow and held in a Universal Pacific 1031 Exchange segregated bank account. Upon purchase of the replacement property(ies), all exchange funds are wired back to the purchase escrow from the Universal Pacific 1031 Exchange segregated bank account upon written authorization from exchanger to release those funds.
Universal Pacific 1031 Exchange carries $2 million of Errors and Omissions insurance.
Your 1031 exchange is only as strong as the intermediary behind it. Many investors mistakenly view all 1031 facilitators as the same, but there's no federal regulation overseeing qualified intermediaries. That means anyone can claim to be a 1031 exchange company, even without experience, oversight, or compliance safeguards. Here’s what shapes how we work:
Every transaction is reviewed by licensed CPAs trained in IRS Section 1031 guidelines, real estate law, and tax deferral strategy.
Your proceeds are never co-mingled. We assign a dedicated bank account to each exchange and require written authorization for any movement of funds.
We don't cut corners. Every deadline, identification rule, and assignment step is followed with precision, because one mistake can trigger full capital gains taxes.
From Los Angeles to Miami, we've supported investors in complex property exchanges involving industrial, multifamily, vacant land, and commercial development deals.
Choosing the wrong qualified intermediary can cost you six figures in tax liability. Choosing the right one unlocks lifetime compounding returns through legal deferral.
Eight interactive calculators — capital gains deferral, boot, deadlines, cap rate and more. Everything runs right here in your browser; nothing leaves your device.
Estimate the federal capital-gains tax, depreciation recapture, NIIT and state tax you can defer with a properly structured 1031 exchange.
Open tool →Calculate the capitalization rate of an income property from its net operating income and value.
Open tool →Estimate total and simple annualized return on investment for a property purchase and hold.
Open tool →Estimate federal depreciation recapture (unrecaptured §1250 gain), §1245 recapture, residual capital gain, NIIT and California tax using the Schedule D Tax Worksheet stacking method.
Open tool →Determine taxable boot (cash and mortgage) in a partial 1031 exchange and the federal, NIIT and state tax on it, using the Treas. Reg. §1.1031(d)-2 netting rules.
Open tool →Calculate your 45-day identification and 180-day exchange deadlines from the relinquished property closing date.
Open tool →Understanding 1031 exchanges isn't just about knowing the rules. It's about aligning your tax strategy with your long-term goals while minimizing risk at every step.
At Universal Pacific, our process is built on decades of IRS rulings, industry whitepapers, and in-field tax advisory experience. For a deeper understanding of 1031 exchanges, review the IRS 1031 Exchange Overview and the Miscellaneous Qualified Intermediary Information Overview. While the technical foundations remain consistent, the way your intermediary interprets and applies them makes all the difference.
This is where most 1031 exchange companies fall short—and where we build our reputation. Investors who prioritize precision, security, and tax compliance don't just rely on federal guidelines—they rely on experts who live and breathe them daily.
The owner of the property and the Qualified Intermediary enter into an exchange agreement on or before the date of the sale (delayed exchange) or purchase (reverse exchange) providing:
Check out our blog to learn more about the process.
You find the right replacement property, but you are not ready to sell your current property yet. A reverse 1031 exchange lets you buy the new property first and sell the old one later. The IRS has a safe harbor for these transactions, but the financing can be difficult. You need a plan for how […]

Working out how much of your sale proceeds actually has to go into the next property is the part of a 1031 exchange that keeps most investors up at night. To defer all capital gains tax, you must reinvest the entire net sale proceeds and acquire replacement property worth at least as much as the […]

Yes, you can complete a 1031 exchange with a related party, but two extra rules apply on top of the usual ones. Section 267(b) decides who counts as related, and the list is narrower than most people assume. Section 1031(f) then requires both sides to hold their properties for two years after the exchange, or […]
The questions investors ask us most — grouped so you can find the answer that fits your exchange.
More FAQs →A taxpayer must not receive "boot" from an exchange in order for a Section 1031 exchange to be fully tax-deferred. Any boot received is taxable to the extent of gain realized on the exchange. This is acceptable when a seller desires some cash and is willing to pay some taxes. Otherwise, boot should be avoided in order for a 1031 exchange to be tax free.
The term "boot" is not used in the Internal Revenue Code or the Regulations, but is commonly used in discussing the tax consequences of a Section 1031 tax-deferred exchange. Boot received is the money or the fair market value of "other property" received by the taxpayer in an exchange. Money includes all cash equivalents plus liabilities of the taxpayer assumed by the other party, or liabilities to which the property exchanged by the taxpayer is subject.
Boot can be inadvertent and result from a variety of factors. The most common sources of boot include:
If proceeds of sale are used to service non-transaction costs at closing, the result is the same as if the taxpayer received cash from the exchange and then used the cash to pay these costs. Taxpayers are encouraged to bring cash to the closing of the sale of their relinquished property to pay for rent prorations, tenant damage deposits transferred to the buyer, property tax prorations, and any other charges unrelated to the closing.
Cash boot is usually "net cash received" at the closing of either the relinquished or the replacement property. Debt reduction boot occurs when a taxpayer's debt on replacement property is less than the debt on the relinquished property—which happens when a taxpayer is "trading down."
Only the net boot received by a taxpayer is taxed. Cash boot paid offsets cash boot received (but only at the same closing table). Debt incurred on the replacement property offsets debt-reduction boot received on the relinquished property. Debt boot paid never offsets cash boot received—net cash boot received is always taxable. Exchange expenses paid offset net cash boot received.
Exchange Agreement
The owner of the property and the Qualified Intermediary enter into an exchange agreement on or before the date of the sale (delayed exchange) or purchase (reverse exchange) providing:
The sale of exchange property and the purchase of the exchange property are interdependent, that is, they both must happen for the exchange to be complete.
The exchange agreement must contemplate a reciprocal transfer rather than a transfer of property for money consideration only.
Access to the funds is restricted so the owner is not considered to be in receipt of the funds.
Contract Assignment
The sale agreement for the asset to be sold must be assigned to the Qualified Intermediary prior to the date of the sale.
The purchaser must acknowledge the assignment on or before the date of the sale in order for the asset to be sold.
The purchase agreement for the replacement property must be assigned to the Qualified Intermediary.
The seller of the replacement property must acknowledge the assignment on or before the date of the purchase.
A Taxpayer Must Not Receive “Boot” from an exchange in order for a Section 1031 exchange to be 1031 exchange. Any boot received is taxable (to the extent of gain realized on the exchange). This is okay when a seller desires some cash and is willing to pay some taxes. Otherwise, boot should be avoided in order for a 1031 Exchange to be tax free.
The term “boot” is not used in the Internal Revenue Code or the Regulations, but is commonly used in discussing the tax consequences of a Section 1031 tax-deferred exchange. Boot received is the money or the fair market value of “other property” received by the taxpayer in an exchange. Money includes all cash equivalents plus liabilities of the taxpayer assumed by the other party, or liabilities to which the property exchanged by the taxpayer is subject to. “Other property” is property that is non-like-kind, such as personal property received in an exchange of real property, property used for personal purposes, or “non-qualified property.” “Other property” also includes such things as a promissory note received from a buyer (Seller Financing).
Boot can be in advertent and result from a variety of factors. It is important for a taxpayer to understand what can result in boot if taxable income is to be avoided. The most common sources of boot include the following:
Sale proceeds being used to service costs at closing which are not closing expenses. If proceeds of sale are used to service non-transaction costs at closing, the result is the same as if the taxpayer received cash from the exchange, and then used the cash to pay these costs. Taxpayers are encouraged to bring cash to the closing of the sale of their relinquished property to pay for the following non-transaction costs:
Rent prorations.
Rent prorations.
Tenant damage deposits transferred to the buyer.
Property tax prorations? Maybe, see explanation below.
Any other charges unrelated to the closing.
Cash boot received during the exchange. This will usually be in the form of “net cash received” at the closing of either the relinquished property or the replacement property.
Debt reduction bootwhich occurs when a taxpayer’s debt on replacement property is less than the debt which was on the relinquished property. Debt reduction boot can occur when a taxpayer is “trading down” in the exchange.
Property tax prorations on the relinquished property settlement statement can be considered as service of debt based on PLR 8328011. Under this rationale exchange cash used to service tax prorations should not result in taxable boot. However, taxpayers may want to bring cash to the relinquished property closing anyway in order to resolve this issue.
Excess borrowing to acquire replacement property. Borrowing more money than is necessary to close on replacement property will cause cash being held by an Intermediary to be excessive for the closing. Excess cash held by an Intermediary is distributed to the taxpayer, resulting in cash boot to the taxpayer. Taxpayers must use all cash being held by an Intermediary for replacement property. Additional financing must be no more than what is necessary, in addition to the cash, to close on the property.
Loan acquisition costs with respect to the replacement property which are serviced from exchange funds being brought to the closing. Loan acquisition costs include origination fees and other fees related to acquiring the loan. Taxpayers usually take the position that loan acquisition costs are being serviced from the proceeds of the loan. However, the IRS may take a position that these costs are being serviced from Exchange Funds. This position is usually the position of the financing institution also. There is no guidance in the form of Treasury Regulations on this issue at the present time which is helpful.
Non-like-kind property which is received from the exchange, in addition to like-kind property (real estate). Non-like-kind property could include the following:
Seller financing, promissory note.
Sprinkler equipment acquired with farm land.
Ditch stock in a mutual irrigation ditch company acquired with farm land (possible issue).
Big T Water acquired with farm land (possible issue).
Acquisition of ditch stock or Big T water is a possible issue with the IRS. Most taxpayers report their exchanges of farm land by taking the position that water on the farm land is indistinguishable from, and the same thing as real estate. The IRS has been known to have a different view.
Boot Offset Rules – Only the net boot received by a taxpayer is taxed. In determining the amount of net boot received by the taxpayer, certain offsets are allowed and others are not, as follows:
Cash boot paid offsets cash boot received (but only at the same closing table).
Cash boot paid at the replacement property closing table does not offset cash boot received at the relinquished property closing table (Reg. §1.1031(k)-1(j)(3) Example 2). This rule probably also applies to inadvertent boot received at the relinquished property closing table because of prorations, etc. (see above).
Debt incurred on the replacement property offsets debt-reduction boot received on the relinquished property.
Cash boot paid offsets debt – reduction boot received.
Debt boot paid never offsets cash boot received (net cash boot received is always taxable).
Exchange expenses (transaction and closing costs) paid (relinquished property and replacement property closings) offset net cash boot received.
Rules of Thumb:
Always trade “across” or up. Never trade down (the “even or up rule”). Trading down always results in boot received, either cash, debt reduction or both. The boot received can be mitigated by exchange expenses paid.
Bring cash to the closing of the relinquished property to cover charges, which are not transaction costs (see above).
Do not receive property which is not like-kind.
Do not over-finance replacement property. Financing should be limited to the amount of money necessary to close on the replacement property in addition to exchange funds which will be brought to the replacement property closing.
Speak with a CPA-led qualified intermediary. We line up your exchange before you sell — not after.